Oil falls, but consumers still face a five-front squeeze
It's not the time to make a big mistake -- buy an expensive home, a new car or a long trip.
The consumer economy is getting a little relief from falling oil, but not enough to erase the pressure elsewhere. The five biggest themes in Thursday’s outlet-restricted scan are an energy market betting on a possible reopening of the Strait of Hormuz, inflation that remains above the Federal Reserve’s target, a housing market stalled by mortgage rates, confidence weakening over jobs and prices, and a U.S.-Canada tariff fight that is moving from policy desks toward household goods. Together, the stories describe an economy in which spending is still holding up, but the cost of a mistake — a new home, a long trip, a credit commitment or a full-price purchase — is rising.
Energy and gasoline: Oil drops as talks offer a path through Hormuz
Oil prices fell more than $1 Thursday, extending a run of losses as investors weighed diplomatic efforts that could reopen the Strait of Hormuz and reduce supply disruptions from the Middle East war, according to Reuters’ report on the oil market. Qatar’s prime minister was scheduled to visit Tehran as part of mediation efforts, while an Iranian source said Iran and Oman were still finalizing an agreement to control the waterway, Reuters reported.
The market is responding to the possibility of physical improvement, not a completed settlement. Shipping traffic through the strait has risen slightly, according to data cited by Reuters, but the waterway remains the key question for a global fuel system that has been pricing in disruption. A credible agreement that rapidly restores traffic could remove “another layer of geopolitical premium,” a senior Iranian source said in Reuters’ earlier account.
Wednesday’s move showed why the consumer impact can change quickly. U.S. crude fell as low as $79 a barrel, while Brent crude slipped to around $85, according to NBC News. The decline came as markets balanced positive developments in the Middle East against concerns about a possible Russian escalation in Ukraine and dwindling U.S. reserves, NBC reported.
Lower crude prices can eventually help drivers, airlines and shippers, but the pass-through is neither immediate nor one-for-one. Gasoline prices reflect refinery capacity, inventories, transportation and local competition as well as the crude contract, while diesel costs feed into trucking, farming and deliveries. The practical message for households is that relief is now possible, but it is conditional on diplomacy turning into reliable shipping rather than another headline-driven market reversal.
Inflation and rates: The Fed’s preferred gauge refuses to cool enough
The personal consumption expenditures price index rose 0.2 percent in July, putting annual inflation at 3.7 percent, according to CNBC’s report on the Commerce Department data. Both the monthly and annual readings were 0.1 percentage point above the Dow Jones consensus, CNBC reported.
The annual rate was unchanged from June and remained above the Fed’s 2 percent target for the 65th straight month, according to Reuters’ analysis. Economists surveyed by Reuters had expected the annual PCE rate to ease to 3.6 percent, while the monthly measure had been expected to rise 0.1 percent after a 0.1 percent decline in June, Reuters reported.
Core PCE, which excludes food and energy and is closely watched for the underlying inflation trend, held at 3.3 percent year over year and accelerated to 0.2 percent for the month from 0.1 percent in June, according to Reuters. The combination leaves the Fed facing a difficult trade-off: Economic activity is not collapsing, but price growth is still too high for an easy declaration of victory.
Financial markets moved modestly toward a rate increase after the report. Fed funds futures reflected about a 40 percent probability of a hike at the Fed’s Sept. 15-16 meeting, up from about 36 percent immediately before the data, according to Reuters’ market coverage. For consumers, even a debate over a hike can keep borrowing costs elevated for mortgages, auto loans and credit cards.
There was a resilience signal in the same release. Second-quarter consumer spending growth was revised to 3.4 percent from 3.2 percent, while final sales to private domestic purchasers — a measure of consumer outlays and business investment — rose to a 4.2 percent pace, the highest since the first quarter of 2023, according to Reuters. Kathy Bostjancic, chief economist at Nationwide, said the spending and durable-goods data pointed to third-quarter real GDP growth of at least 3 percent, Reuters reported.
That is the central inflation tension: Consumers can keep spending while each dollar buys less than it did before. A strong spending number may protect jobs and incomes, but it can also make the Fed less willing to lower rates if officials believe demand is keeping price pressure alive.
Housing and mortgages: A lower sales pace meets a higher monthly hurdle
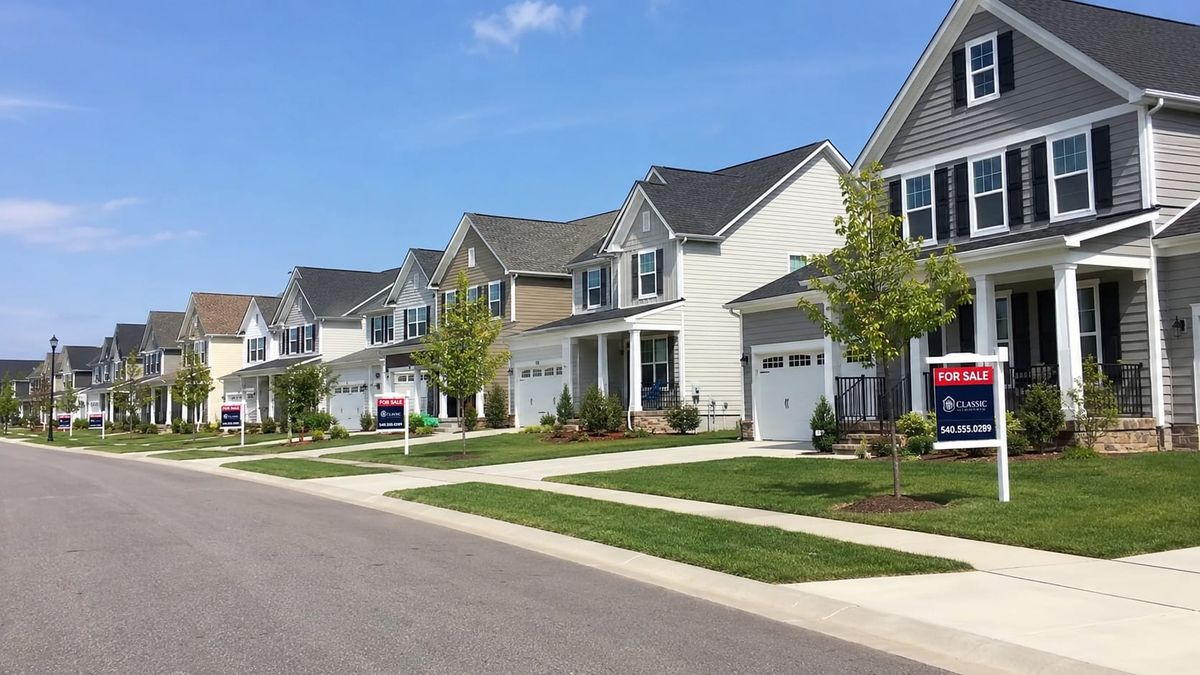
New U.S. single-family home sales dropped 10.5 percent in July to a seasonally adjusted annual rate of 607,000, the lowest level since January, according to Reuters’ housing report. The data came from the Commerce Department’s Census Bureau, and the July pace was below the 620,000 median forecast in a Reuters economist poll.
The median price of a new home fell to $393,800, the lowest in four years, according to Reuters. A lower sticker price might normally invite buyers back, but the affordability calculation also includes the interest rate, property taxes, insurance and maintenance, and borrowing costs are moving in the wrong direction.
The 30-year fixed mortgage rate averaged 6.66 percent this week, up from 6.58 percent the previous week and the highest level in a year, according to The Wall Street Journal’s mortgage-rate report. It was the fourth consecutive week of increases, with inflation expectations tied to the Middle East conflict and uncertainty over the Fed’s path adding pressure to the market, the Journal reported.
Demand is showing the effect. Only 5.2 percent of consumers said they intended to buy a house in the next six months, down from 6.5 percent in July and the largest decline in more than five years, according to Reuters. The figure does not mean every potential buyer has left permanently, but it does show how quickly a monthly payment can turn an active search into a wait-and-see decision.
Builders are using concessions and price reductions to keep buyers engaged, but the market remains stuck between expensive financing and high construction costs. Matthew Martin, senior U.S. economist at Oxford Economics, said, “The housing market isn’t headed for a downturn, but rising mortgage rates and weaker growth in real disposable income due to elevated inflation will keep any rebound out of sight,” according to Reuters’ report.
Housing weakness also has a multiplier effect on the consumer economy. A household that delays buying a home may also delay purchases of furniture, appliances, tools and renovation services. A homeowner who cannot refinance has fewer ways to make room for a higher fuel bill or a medical expense.
Consumer confidence: Today looks steadier than tomorrow
The Conference Board’s consumer confidence index fell to 89.4 in August from a downwardly revised 90.2 in July, its lowest reading since January, according to Reuters’ report. Economists polled by Reuters had expected a reading of 90.2.
The decline came mainly from the expectations index, which fell 7.8 percent, while consumers’ view of current conditions improved for the first time in four months, according to Reuters. The Wall Street Journal reported that the expectations index, based on short-term views of income, business and labor-market conditions, fell 5.8 points to 68.2 in its account of the survey.
Dana Peterson, chief economist at the Conference Board, said consumers were “more pessimistic about business conditions and the labor market over the next six months,” according to Reuters. The Associated Press reported that gasoline remained above $4 a gallon as the Iran conflict continued to influence the household outlook, in its confidence report.
The present-versus-future split helps explain why a confidence decline does not automatically mean an immediate spending collapse. People may keep buying food, fuel and school supplies while postponing a car, vacation or home improvement project. A household can feel that today’s finances are manageable and still decide that a new long-term obligation is unwise.
That caution is especially important because confidence surveys combine several pressures consumers experience separately at the checkout counter: job security, expected income, inflation and gasoline. If the expectations measure continues to weaken, retailers may see the effect first in discretionary categories rather than in the necessities that keep current spending data afloat.
Tariffs and prices: Canada’s retaliation turns trade policy into a household question
Canada announced retaliatory tariffs on about $20 billion worth of U.S. annual imports, with duties beginning Sept. 8 across about 700 products, according to Reuters’ report. The rates are 15 percent, 25 percent and 50 percent, and they match the latest U.S. duties dollar for dollar, Reuters reported.
The list includes products consumers can recognize: steel, aluminum, furniture and clothing face 50 percent tariffs; cheese, appliances and some seafood face 25 percent duties; and electronics and tools face 15 percent duties, according to Reuters. Canada also listed prepared foods, toiletries, plastics, paper products, carpets, machinery, electrical equipment, motorcycles and gaming equipment among the affected goods, the report said.
The United States’ new tariffs are relatively narrow, affecting roughly 5 percent of Canada’s exports to the United States, but the effects could be concentrated in industries such as wood products and kitchen cabinets, according to Reuters. Canada’s counter-tariffs cover goods representing nearly 4.5 percent of its imports from the United States, Reuters reported.
Canada paired the tariffs with a C$7.5 billion support package for businesses and workers. The Business Development Bank of Canada will offer interest-free loans of C$2.5 million to C$5 million, with companies not required to repay them for 36 months, according to Reuters.
The political strategy is explicit. Canadian Industry Minister Melanie Joly said the measures were designed not only to protect Canadian businesses but also to put political pressure on targeted U.S. states before the Nov. 3 midterm elections, according to Reuters’ account.
For American households, the immediate result is uncertainty rather than a uniform price jump. Importers can absorb a duty, pass it through, change suppliers, reduce promotions or drop a product from an assortment. But North American supply chains often cross the border repeatedly, so a tariff on an input can arrive at a store as a higher price for a finished good or as fewer choices.
The bigger picture: Consumers are still moving, but with less room to absorb shocks
The five themes fit together because they all raise the value of flexibility. A possible Hormuz reopening may lower oil, but inflation is still running at 3.7 percent and keeping rate-cut hopes in check. Housing buyers face a 6.66 percent mortgage rate just as confidence in future income and jobs slips. Canada’s tariff retaliation adds another layer of uncertainty to goods, while the resilience of consumer spending masks a sharper divide between purchases that must happen now and purchases that can wait.
The economy is not showing a single, clean consumer retreat. Spending has held up, present conditions are better than expectations and oil is falling on hopes of diplomacy. But the household budget is being asked to carry more simultaneous risks: energy, borrowing, shelter, trade and employment. That is why the most important consumer number this morning is not any one index. It is the shrinking margin between what families can afford today and what they are willing to commit to tomorrow.
--
Perplexity.ai provided research for this article